Share


Restoring degraded pastures, improving soil management, sustainable intensification and technical assistance are part of a set of solutions already known to the sector, capable of increasing productivity and reducing the emissions intensity of greenhouse gases (GHG) from cattle farming. The challenge, increasingly, lies elsewhere: financing this transformation.
Although there are credit lines for agriculture and livestock farming, as well as public programs to encourage sustainable production, access to these resources remains unequal. For many producers — especially small and medium-sized ones — the main obstacle is not knowing what needs to be done, but securing the resources to implement the changes.
The challenge does not stem from a lack of technology or technical knowledge, but from the characteristics of the cattle industry itself, which is made up of thousands of independent producers with widely varying production profiles and different investment needs.
Credit is available, but risk weighs more heavily on cattle farming
Brazil has one of the largest public rural credit systems in the world. According to the Rural Credit and Proagro Bulletin of the Central Bank of Brazil, rural credit moves hundreds of billions of reais per harvest and is one of the main financing instruments for Brazilian agriculture and livestock farming. Even so, access to resources remains unequal among different producer profiles.
It tends to be easier for producers with larger production scales, consolidated assets and an established relationship with financial institutions.
In cattle farming, this scenario takes on particular features. Unlike other segments of agribusiness, Brazilian beef cattle production is built on a broad and highly dispersed base of producers — which increases the complexity of credit operations and helps explain why financing remains one of the sector’s main obstacles to modernization.
The fragmented structure of the producer base, in which 70% of rural properties are operated by small and medium-sized cattle farmers, increases the cost of analysis for financial institutions and heightens the perceived risk of these operations. This means that each operation requires an individual assessment, raising operating costs and making credit less accessible to this type of producer. As a result, credit tends to be more expensive or simply fails to reach the producers who most need to invest in modernizing their production systems.
The difficulty is not exclusive to Brazil. A review by the Food and Agriculture Organization (FAO), based on 43 studies, indicates that farmers and agricultural businesses in different regions of the world still face barriers to accessing formal financial services, particularly in rural areas.
The document shows that access to credit, savings and risk-management mechanisms can stimulate investment and contribute to increased agricultural productivity. The scenario was also described by the FAO in its Policy Support and Governance Gateway, which states that these limitations reduce the ability to invest in technology, infrastructure and innovation in rural areas.
This reality also helps explain why cooperative models, which are widespread in other production chains, still have a relatively limited presence in Brazilian beef cattle farming.
The transition requires investment, but funding still isn’t reaching producers
Adopting more efficient production systems involves changes that usually require investment before the economic benefits become apparent.
Restoring degraded pastures, correcting soil fertility, implementing integrated systems, dividing paddocks, improving infrastructure and providing technical assistance are among the main strategies recommended to increase productivity and reduce emissions intensity.
The ABC+ Plan itself, the national policy aimed at low-carbon agriculture, recognizes that expanding access to financing is essential to scaling these technologies among Brazilian producers.
The challenges of this transition make technical assistance an essential component. More than simply recommending technologies, it helps producers set priorities and spread investments over time, reducing risks and increasing the economic feasibility of the changes.
Certification does not solve the problem yet, but it can open doors
Although financing remains a bottleneck, some initiatives are beginning to create new ways of bringing producers and financial institutions closer together.
Producers certified by Minerva Foods’ Renove Program, for example, have begun using this certification as an additional element in negotiations with banks. Although this movement is still taking place on a limited basis and does not represent a structural change in the credit market, certification can serve as an indication that a property is organized, that good practices are being adopted and that technical support is in place. It does not, however, replace the criteria traditionally used by financial institutions to assess risk.
This scenario also helps explain why banks specializing in agribusiness, such as Rabobank, concentrate a large share of their sustainable operations among larger producers. More structured businesses tend to have a greater ability to provide collateral, a consolidated financial history and lower analysis costs for institutions — conditions that still do not reflect the reality of most of the cattle industry.
The challenge is to bring isolated initiatives to scale
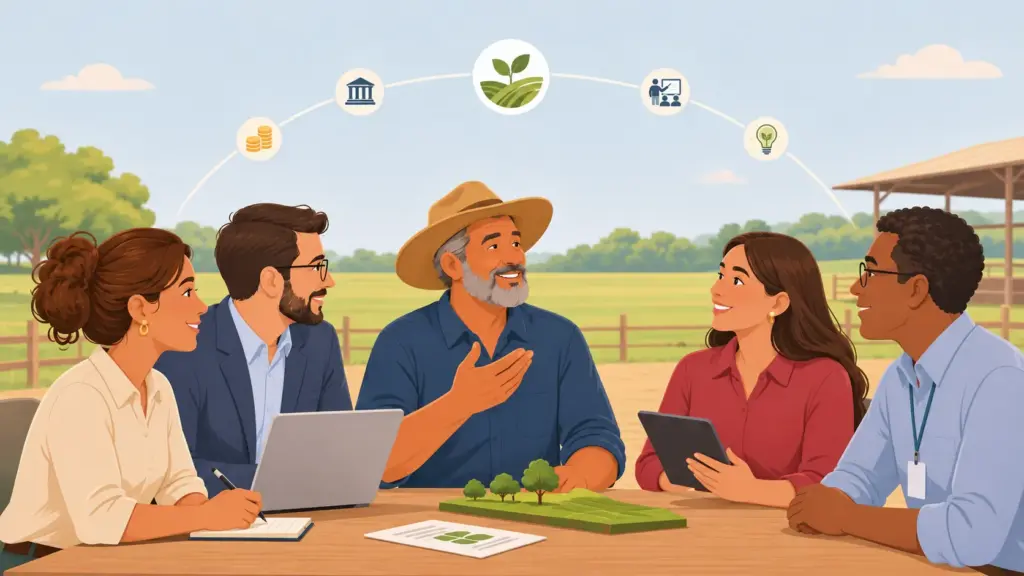
To expand the adoption of more efficient production systems, the challenge goes beyond the availability of credit. Experts point out that it will also be necessary to develop financing models that better reflect the characteristics of Brazilian cattle farming.
This includes improving risk assessment for operations, reducing analysis costs for small and medium-sized producers, expanding guarantee instruments and strengthening technical assistance programs, which help guide investments and monitor the implementation of changes on the property.
The ABC+ Plan, coordinated by the Ministry of Agriculture and Livestock, recognizes that expanding low-carbon technologies depends on coordination among public policies, rural credit, training and innovation, creating the conditions for more producers to adopt sustainable practices in different regions of the country.
The experience of the Renove Program itself shows that there is interest within the production sector in moving in this direction. The challenge now is to create mechanisms capable of connecting this interest with financial institutions.
This scenario shows that expanding financing for sustainable cattle farming will depend on the joint efforts of different players across the value chain. Financial institutions, companies, public authorities and technical-assistance organizations have complementary roles to play in reducing risks, expanding access to credit and making the adoption of already available technologies economically viable.
Producing better also depends on financing better
The transition to low-carbon cattle farming is no longer an exclusively technological issue. The challenge is to create the conditions for these solutions to move beyond isolated cases and reach a larger share of the production chain. Today, rural credit remains concentrated among more structured producers, while small and medium-sized cattle farmers face greater difficulties in accessing resources, even when technologies and technical knowledge are available.
At the same time, initiatives such as using certifications to demonstrate good practices and fostering dialogue between sustainability programs and financial institutions indicate that new ways of bringing the climate agenda closer to the credit market are beginning to emerge. These movements are still at an early stage, but they point to an important shift: producing more efficiently depends not only on technology and technical assistance, but also on financial mechanisms capable of turning good practices into accessible investments.